Table of Contents
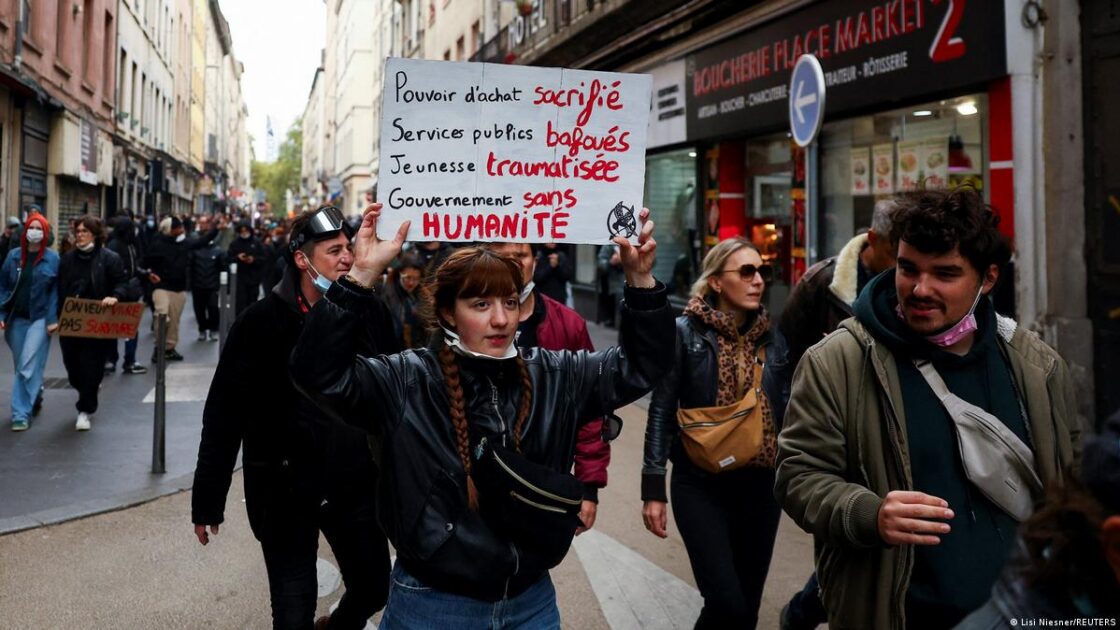
France is grappling with a severe economic predicament characterized by high public debt, a government without a parliamentary majority, and intense political gridlock between extremist factions. Amid nationwide protests, the government has promised billions in new funding for schools and universities, raising concerns because the state lacks the necessary financial resources.
A Barometer of Public Finances
France’s public debt currently hovers around 120% of its gross domestic product (GDP), contrasting sharply with Germany’s debt-to-GDP ratio of roughly 65%. While Germany maintains a top-tier AAA credit rating and a stable outlook, credit agencies rate France lower at AA, A+, or Aa3 and assign it a negative outlook. Consequently, as Deutsche Welle: DW.com reported, France must pay significantly higher interest rates on borrowing, with the risk premium over German bonds reaching its highest level since the financial crisis.
Friedrich Heinemann, an economist at the Leibniz Center for European Economic Research (ZEW) in Mannheim, told Deutsche Welle: DW.com that this spread functions as a critical fever gauge for bond markets. He explained that if the spread rises too sharply, it pressures France’s financing conditions, forces higher loan rates for citizens, destabilizes banks, and potentially triggers a financial crisis. Conversely, Landry Charrier, a researcher at the University of Bonn, told Deutsche Welle: DW.com that the debt remains an abstract concept for many citizens because 56% of the population receives more in government benefits than they pay in taxes, giving the majority a vested interest in maintaining the status quo. France has not balanced its national budget in over half a century, with its last balanced budget occurring in 1974.
Echoes of the Eurozone Crisis
France last faced a similarly high-risk premium at the end of 2011 during the eurozone debt crisis, though the recent spread over German bonds has more than doubled since June 2026. This escalation is driven primarily by the high debt load, political instability, large budget deficits, and recent unrest, leading to surging debt-servicing costs. France anticipates paying more than €79 billion in interest on its public debt in 2026, with projections exceeding €91 billion in 2027 and reaching between €125 billion and €132 billion by 2030, according to figures that include social security funds and local authorities.
The Agence France Tresor estimates the central government’s annual interest bill alone at €62.6 billion. As large amounts of low-interest bonds mature, France must refinance them while simultaneously taking on new debt to cover its budget deficit. Meanwhile, rising interest costs are also beginning to impact Germany, where Heinemann calculates that federal interest payments will triple from around €30 billion to exceed €90 billion by the early 2030s.
Political Polarization and Fairy Tales
In France, political debates largely ignore these worsening economic realities, as both the far-right National Rally (RN) and the far-left La France insoumise (LFI) campaign on expensive promises. RN leader Marine Le Pen seeks to reinstate the retirement age at 62 while promising €140 billion in savings, whereas LFI leader Jean-Luc Melenchon has suggested that government bonds held by the French central bank could simply be destroyed. Heinemann criticized these platforms as economic fairy tales that falsely promise an escape from the crisis without fiscal consolidation or painful cuts.
Charrier added that many French citizens fail to appreciate the urgency of the situation because the euro has historically provided easy access to cheap financing and eliminated the warning signals once delivered by currency devaluations of the French franc. Without the immediate impact of declining purchasing power and rising prices, an illusion has formed that essential economic adjustments can be indefinitely postponed.
This piece was originally published in German.